The opening of a dedicated bank account is a fundamental step for any association law 1901. Although the law does not require this separation for very small structures, it becomes essential if the association collects contributions, receives grants or settles invoices. Rigorous financial management is the first guarantee of transparency vis-à-vis your members and public partners.
Contents
Why open a bank account dedicated to your association?
The confusion between the treasurer's or president's personal assets and the association's resources creates legal and tax risks. By centralizing flows to a specific account, you ensure that traceability of operationsThis facilitates annual accounting. An association that develops can quickly undergo administrative complexity if financial flows are not centralized, making the justification of expenses and revenues laborious at general meetings.
Many institutions require a bank identity statement (BID) on behalf of the association to pay grants or allow payment by cheque or transfer. Having a clean account strengthens the credibility of your structure with suppliers and banking institutions.
The procedures and documents necessary for the opening
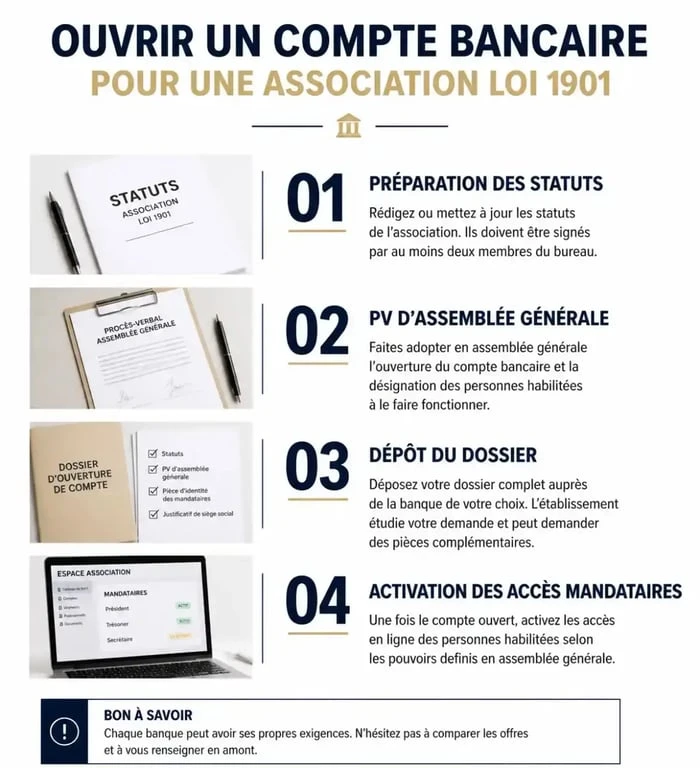
Opening a bank account for an association requires administrative preparation. The bank must verify the legal existence of your structure and the identity of the persons empowered to manage it.
Mandatory supporting documents
To prepare your file, you must provide the following documents to the bank:
- The statutes of the association Dated and signed by the founding members.
- Declaration receipt in prefecture : proving that the association is officially registered.
- The extract from the Official Journal : attesting to the publication of the creation.
- Minutes of the General Meeting This document must explicitly designate the persons authorized to open and operate the account.
- Identity documents : representatives designated in the PV.
- A proof of registered office : like an electricity bill or a rental lease.
The role of representatives
The minutes are the backbone of your relationship with the bank. He mentioned the powers granted to members of the Bureau. If more than one person is required to sign cheques or make transfers, this must be recorded in writing. Any changes to the bureau members, such as a change of president or treasurer, require a new VP and an update of the powers with your bank advisor.
The right to account: what to do in case of refusal?
A bank may refuse to open an account for an association without justifying its decision. If you have more than one refusal, you can claim your right to account. This procedure is supervised by the Banque de France.
To activate, ask each bank that refused the opening to give you a certificate of refusal. With this document, you can seize the Bank of France. It will designate a banking institution to open an account with your association. At a minimum, this account should provide access to basic banking services.
Basic banking services and features included
When a bank opens an account, notably via the account entitlement, it provides a range of essential services for the association's current operations.
| Service | Characteristics |
|---|---|
| Opening and accounting | Included |
| Bank cheques | Up to 2 per month |
| Statement of account | At least 1 per month |
| Change of address | 1 time per year included |
| Deposits and withdrawals | Authorized current account |
Some banks offer specific offers including civil liability guarantees. Establishments operate the association up to a ceiling of 50,000 € under package contracts, for structures with a moderate annual budget, often below 500 000 €.
How to choose between traditional bank and online bank?
The choice depends on your service needs and your need for proximity. Traditional banks offer human support, useful if your association manages complex flows or requires a regular cash deposit.
Online banks offer more attractive rates and dematerialised management adapted to small associations with few cash needs. Multi-user management is a key point: check whether the interface creates differentiated access for the president and treasurer to secure transfer validations. Before you commit, compare account keeping costs, transaction fees, and the ease of obtaining a checkbook, a tool that is sometimes indispensable for settling some local providers.
Updated on 15 September 2026